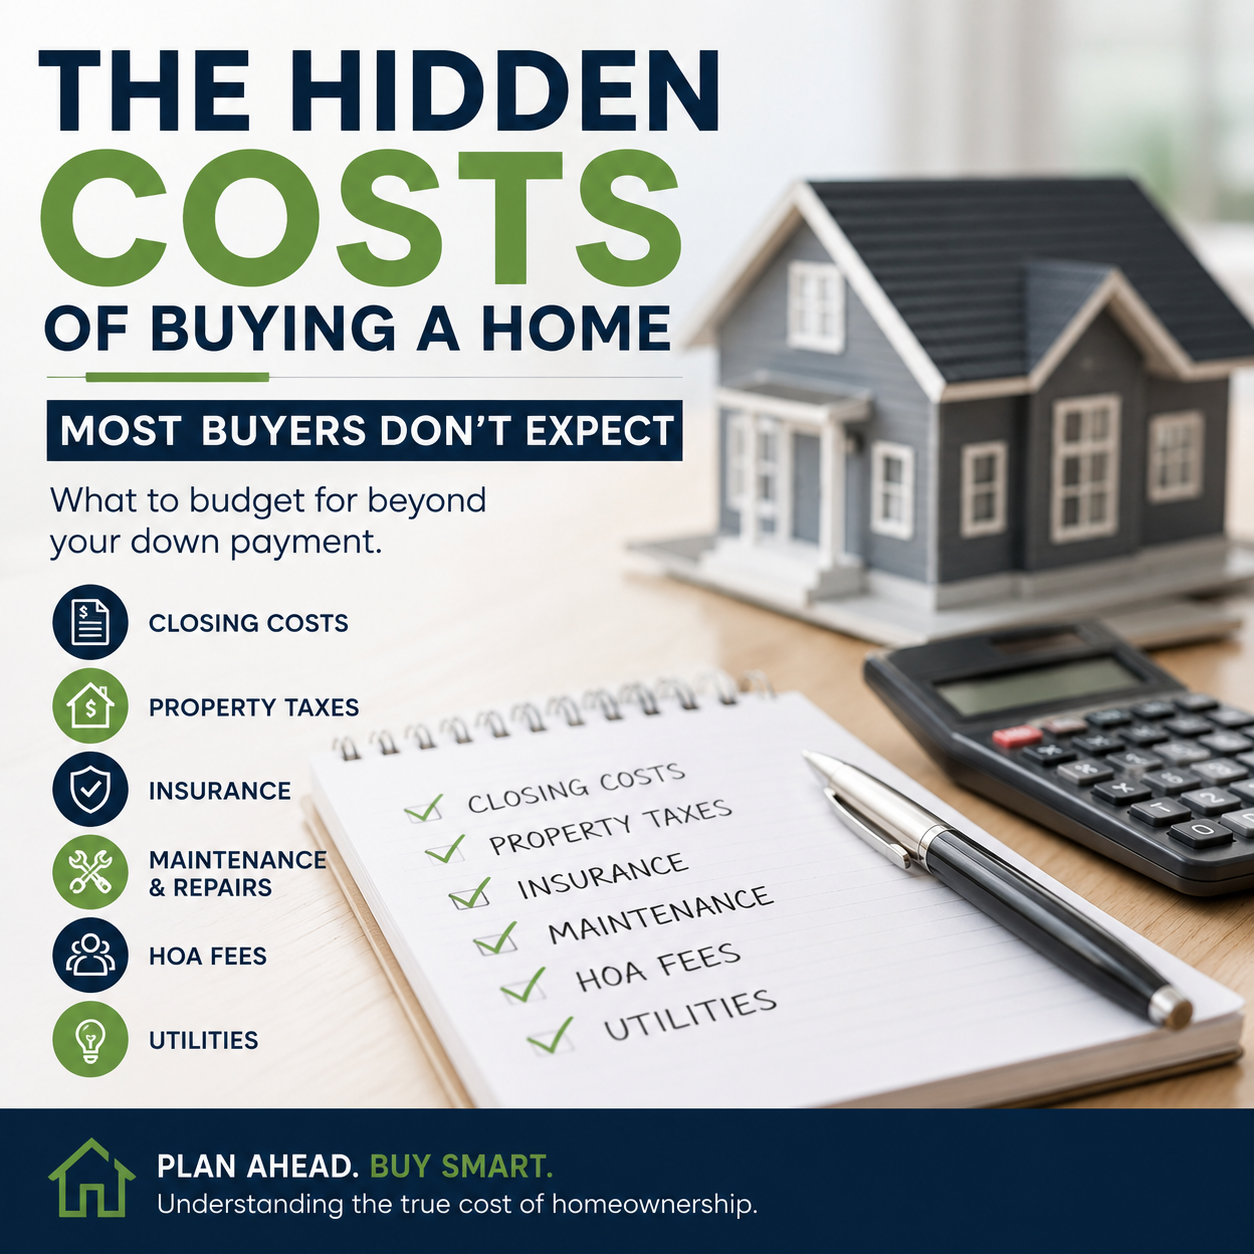
Hidden costs of buying a home can change what feels affordable even when the purchase price and loan payment look comfortable. A useful buyer budget includes the costs to complete the transaction, the expenses of moving in and the ongoing cost of operating the property.
The numbers vary by property, location, lender, insurer, loan type and contract. Treat this as a planning list, then request property-specific estimates from the licensed professionals involved in your purchase.
1. Closing charges and prepaid items
Closing costs may include lender charges, appraisal fees, title-related services, government recording or transfer charges, prepaid interest, insurance and initial escrow deposits. Which party pays a particular item can depend on the loan, contract and applicable rules.
Review the official CFPB Loan Estimate explainer and compare the estimated cash to close—not only the interest rate or principal-and-interest payment.
2. Property taxes
Property taxes vary by jurisdiction and property. Two similarly priced homes may have different tax bills, and a lender’s initial escrow estimate can change. Verify the current tax information and ask how a recent sale, exemption change or reassessment could affect future bills.
3. Homeowners insurance and other coverage
Premiums depend on the property, coverage, deductible, insurer and risk factors. Roof age, prior claims and location may affect availability or cost. Flood, earthquake or other coverage may be separate when relevant. Obtain quotes early enough to identify a concern before a contract deadline.
4. Inspections and specialized evaluations
A general home inspection is a common due-diligence expense, but the property or initial findings may support additional evaluations. Examples can include sewer, septic, well, pest, chimney, structural, roof, environmental or other specialist reviews.
See what to expect from a home inspection when buying a house, then ask which optional evaluations fit the specific property.
5. Appraisal and financing-related costs
When financing is involved, the lender may require an appraisal or another valuation. Some loan programs also involve mortgage insurance, funding fees or other program-specific costs. Ask the lender which charges apply, when they are due and whether any can change.
Our home appraisal guide explains the appraisal’s role in the loan process.
6. Association dues and community costs
A condominium or homeowners association may charge regular dues, transfer or setup fees, special assessments or other amounts. Review the documents and budget for both current dues and potential changes. Association coverage also affects what the owner must insure separately.
7. Moving, setup and immediate purchases
Moving trucks or movers, utility deposits, locks, window coverings, appliances, paint, furniture and basic tools can create a sizable first-month total. Decide what is necessary immediately and what can wait.
8. Maintenance, repairs and utilities
Ownership introduces costs that renters may not have paid directly: HVAC service, filters, lawn care, pest control, plumbing repairs, appliance replacement, roof work and seasonal upkeep. Utility costs can also shift with home size, system efficiency and household use.
Keep in mind: Avoid spending every available dollar on the transaction. A separate post-closing reserve can give you room for ordinary ownership costs and surprises.
Hidden costs of buying a home in the Kansas City region
Buyers comparing Blue Springs, Lee’s Summit, Warrensburg, Raymore, Kansas City and nearby Kansas communities should compare more than list prices. Taxes, insurance, association dues, utility systems, commute costs and property condition can change the monthly picture.
Use the areas served page for local starting points, including the Blue Springs community guide.
A better budget conversation
- Ask the lender for estimated cash to close and total monthly payment.
- Request insurance quotes for the actual property.
- Review available tax and association information.
- Budget for inspection and appraisal steps.
- Keep a moving and immediate-repair allowance.
- Maintain reserves after closing.
Frequently asked questions
Are closing costs the same as a down payment?
No, they’re separate parts of your budget. Your down payment goes toward the purchase price. Closing costs and prepaid items cover other transaction and ownership expenses, though how you pay them can vary.
Can a seller pay some buyer closing costs?
Sometimes. The seller has to agree, and your loan program has to allow the contribution. It’s something you negotiate as part of the offer, so consider it alongside the price and other terms.
How can I estimate the true monthly cost?
Look beyond principal and interest. Include mortgage insurance if it applies, property taxes, homeowners insurance, association dues, utilities and money for maintenance. You can talk with Austin about the real estate questions, and ask licensed financial and insurance professionals for figures and advice specific to you.